21 October 2026
Despite a sharp rise in energy prices in early 2026, the euro area economy has proved resilient. This blog examines how decreased vulnerability to energy shocks, policy support and the global AI upswing have helped cushion the impact, and explores what is needed to sustain that resilience.
The latest shock follows years of economic turbulence. The euro area has navigated the pandemic and post-pandemic global supply shortages, the energy crisis following Russia’s war against Ukraine, Red Sea disruptions to global shipping, and trade tensions linked to US tariffs.[2] Although distinct, the events of early 2026 posed a stern, and still ongoing, challenge to the euro area’s resilience. These events disrupted global energy markets amid geopolitical uncertainty, which can have significant and durable adverse effects on activity and amplify business cycle fluctuations.[3]
A series of shocks
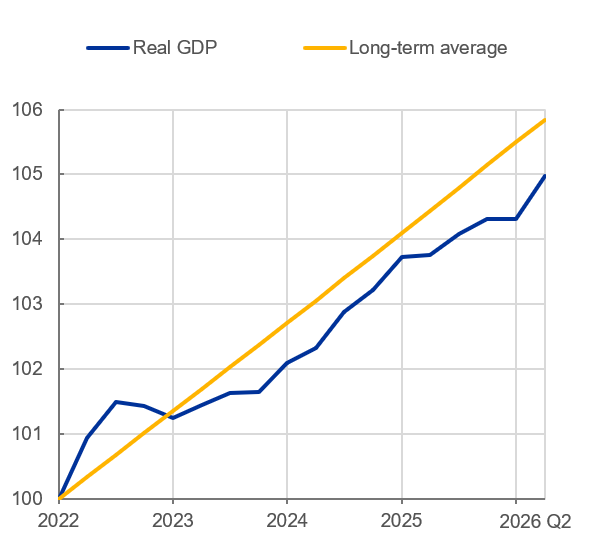
Since 2022 euro area GDP has continued to follow a moderate upward trajectory, despite successive shocks.[4] Adverse shocks have not resulted in declines in output (Chart 1, panel a)[5], even though growth has slowed compared with the long-term average. So far, the latest energy shock has been no exception.
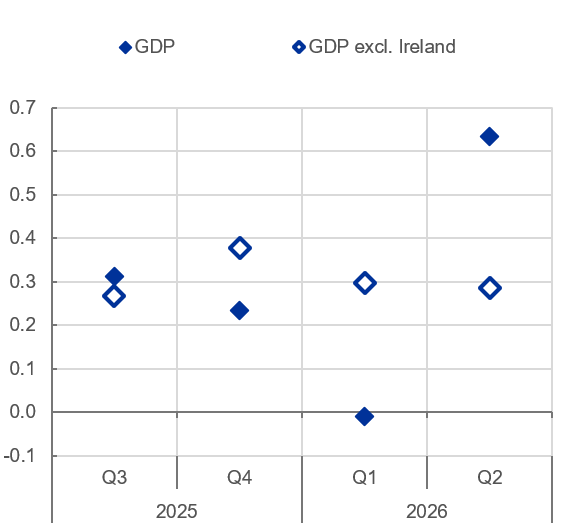
When excluding the volatile Irish data, real GDP in the second quarter of 2026 was 0.6% above the level reached in the fourth quarter of 2025. Incoming data point to a continued expansion. Compared with the previous quarter, the euro area economy (excluding Ireland) has fared better than forecasts expected, with a stable growth rate of around 0.3% in each of the last four quarters (Chart 1, panel b).
This raises an important question: why has the latest energy price shock had only a limited impact on the euro area economy so far?
The concept of economic resilience can help answering this question. It encompasses three complementary dimensions: absorptive capacity, the ability to limit the immediate impact of a shock; recovery capacity, or the ability to return quickly to the pre-shock path; and adaptive capacity, which refers to the ability to adjust economic structures and institutions in ways that reduce vulnerability to future shocks.
The experience of the latest energy shock illustrates how all three dimensions have strengthened in the euro area in recent years, although each also has its limits. It is important to distinguish between lasting structural improvements and support from policy measures and the AI-driven upswing, which may prove more temporary.
Chart 1
Macroeconomic developments in the euro area
|
a) Real GDP – levels |
b) Real GDP – growth |
|---|---|
|
(first quarter of 2022 = 100) |
(quarter-on-quarter percentage changes) |
|
|
|
Source: Eurostat. Notes: Long-term average corresponds to the period 2000-26. The latest observations are for the second quarter of 2026. |
Sources: Eurostat and ECB calculations. Note: The latest observations are for the second quarter of 2026. |
Is the economy less vulnerable to energy shocks?
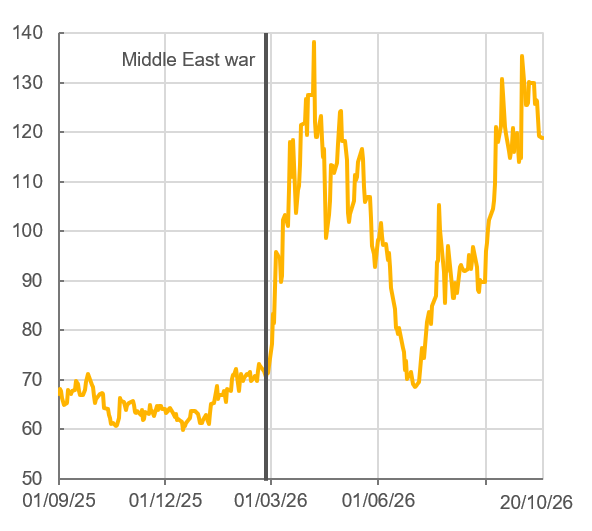
The conflict in the Middle East initially sent oil prices soaring, but they eased after the June US-Iran memorandum of understanding (Chart 2, panel a). A second wave of the shock starting in July saw another significant increase in oil prices, along with sharp increases in refining margins and a sustained rise in gas prices.
The euro area economy has become structurally less exposed to fluctuations in fossil energy commodity prices. This explains why the impact of the latest energy shock has so far been relatively limited. Over the past three decades, firms and households have improved energy efficiency and reduced reliance on oil and gas[6].
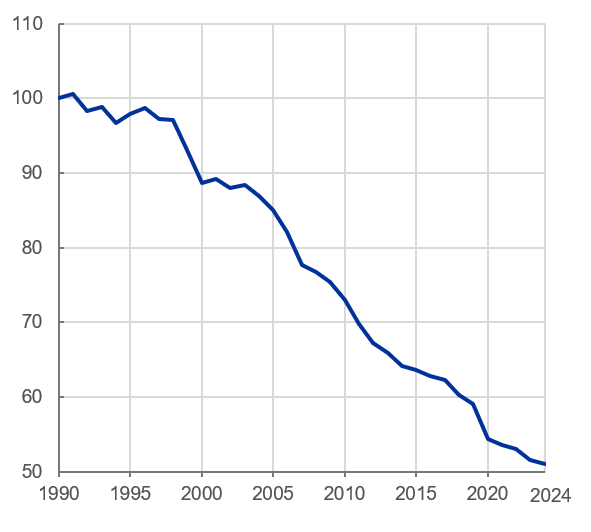
Economic activity has gradually shifted towards less energy-intensive sectors, particularly services. The euro area economy is for example only half as reliant on oil as it was in the early 1990s (Chart 2, panel b).
ECB analysis suggests that this decline has reduced the impact of oil supply shocks on growth, consumption and investment in the euro area, making the economy more resilient.[7] The green transition can reinforce this development, as a growing share of renewable energy reduces the dependence on imported fossil fuels.[8]
This shift is increasingly shaping electricity prices in the euro area. The expansion of renewable generation capacity is reducing wholesale electricity prices in many countries.[9] This is linked to a higher share of renewables reducing the share of hours in which gas-fired plants set the marginal price of electricity, decreasing the pass-through from wholesale gas to electricity prices.
In Spain, for example, where renewable electricity generation is particularly high, the share of hours in which gas plants set electricity prices has fallen from around 80% in 2020 to just above 20% in 2026, considering the first nine months of each year. A similar decline has occurred in France, where nuclear power often dominates the generation mix, with the share falling from around 60% to around 20%.[10] Unlike during the 2021-22 energy shock, when electricity prices closely followed gas prices, the latest shock has had a smaller impact in countries with larger renewable and nuclear energy shares in the first half of 2026.[11]
Although Europe remains exposed to developments in global energy markets, the economy is now less vulnerable to fossil fuel and gas price shocks compared with a few decades ago.
Chart 2
Oil price developments and sensitivity to oil supply shocks
|
a) Oil price |
b) Oil sensitivity of the euro area economy |
|---|---|
|
(USD per barrel) |
(index: 1990 = 100) |
|
|
|
Sources: Bloomberg, Refinitiv and ECB staff calculations. Note: The latest observations are for 20 October 2026. |
Sources: Eurostat, New Area-Wide Model database and ECB staff calculations. Notes: Oil intensity is measured in kilograms of oil equivalent per euro of real GDP and indexed to 100 in 1990. The latest observations are for 2024. |
At the same time, the public sector has been playing a larger role in the economy in the post-pandemic period, acting as a buffer against the impact of the energy shock linked to the conflict in the Middle East.
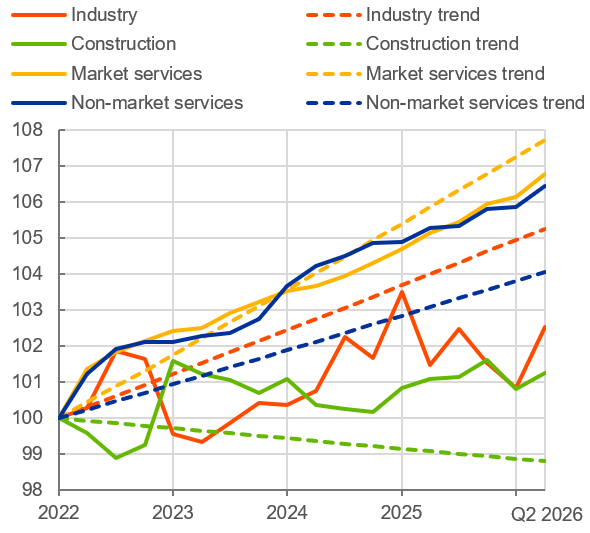
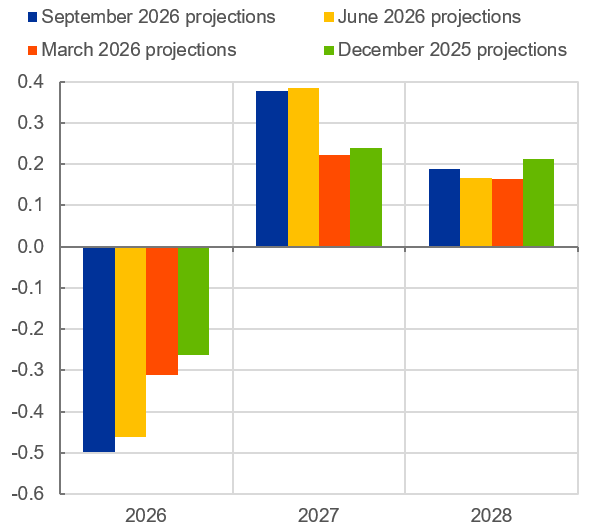
Chart 3, panel a, shows that non-market services have been consistently growing above their long-term average and faster than other sectors in recent years. And fiscal policy has again helped to absorb the energy shock.[12] Fiscal support of the economy, which can be measured by the fiscal stance, has been increasing over the year. While the December 2025 projections expected an expansionary fiscal stance of 0.25 percentage points for 2026, this has gradually increased to reach 0.5 percentage points, thus doubling the expected fiscal support for the euro area economy over 2026 (Chart 3, panel b).[13] This mainly reflects higher spending on defence and infrastructure in Germany, and to a lesser extent, fiscal support measures of euro area countries aimed to cushion the impact of higher energy costs.
However, part of this support is temporary, fiscal space is limited in several countries, and the projections point to less fiscal support in the coming years. Therefore, fiscal policy might not be able to cushion further shocks to the same extent.
Chart 3
Sectoral developments and fiscal stance
|
a) Sectoral developments |
b) Fiscal stance |
|---|---|
|
(index: 2022 = 100) |
(percent of GDP) |
|
|
|
Sources: Eurostat and ECB calculations. Note: Long-term averages (trends) correspond to the period 2000-26. The latest observations are for the second quarter of 2026. |
Sources: September 2026 ECB staff macroeconomic projections, June 2026 Eurosystem staff macroeconomic projections, March 2026 ECB staff macroeconomic projections and December 2025 Eurosystem staff macroeconomic projections. Notes: The fiscal policy stance is measured as the change in the cyclically adjusted primary balance. The figures shown are adjusted for the fact that revenues from grants under the Next Generation EU programme are not withdrawn from the domestic economy. A negative figure implies a loosening of the fiscal stance, while a positive figure implies a tightening of the fiscal stance. |
Which factors supported growth?
Four factors that helped the economy get back on track stand out: a moderation in the degree of uncertainty perceived at the initial stages of the Middle East crisis, a more favourable external environment driven partly by AI, an AI-related boost to domestic investment, and a resilient labour market.
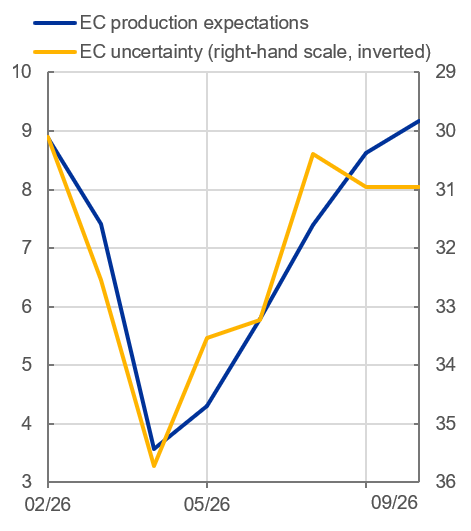
Uncertainty shot up after the start of the conflict. Production expectations collapsed, and uncertainty shot up, amid fears of disruption to energy and non-energy commodities, such as fertilisers, and a swift deterioration in global supply bottleneck indicators.
However, some of these fears started to fade as early as May. Production expectations gradually moved back to their pre-war levels in August and September (Chart 4, panel a). When the worst conflict-related scenarios did not materialise, uncertainty receded and confidence returned, supporting the euro area economy.
Activity may also have been temporarily supported by precautionary behaviour. Because the conflict raised the risk of outright fuel shortages and higher costs, some firms may have brought forward orders and production to secure supplies.
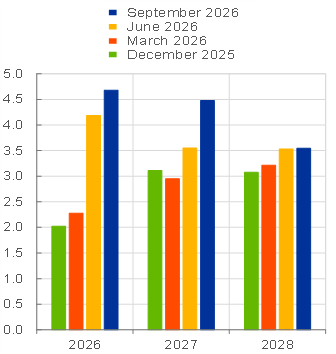
A second factor is that the global environment has been more supportive than many anticipated. While the December 2025 Eurosystem staff macroeconomic projections expected global trade to grow by 2%, the latest projections see global trade growth in 2026 as more than twice as high, at 4.7% (Chart 4, panel b).
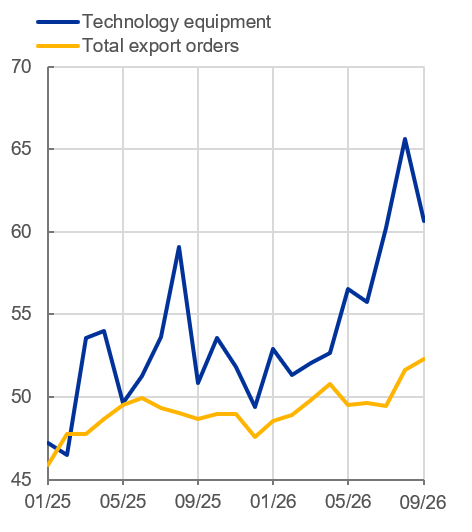
Strong AI-related trade is an important driver of this more positive outlook. AI-related trade has provided an important tailwind for the euro area economy, helping to cushion the effects of the energy shock.[14]As a highly open economy, the euro area benefited from stronger external demand for capital goods and specialised manufacturing products linked to AI-related investment, as reflected in the development of Purchasing Managers’ Index (PMI) export orders for technology equipment (Chart 4, panel c).
Chart 4
Uncertainty, world imports and euro area exports
|
a) Uncertainty and production expectations |
b) World imports (excluding euro area) |
c) PMI export orders |
|---|---|---|
|
(percentage balances) |
(annual percentage changes) |
(diffusion indices) |
|
|
|
|
Source: EC (European Commission). Notes: The production expectations and uncertainty measures are weighted averages for industry, services and retail. The latest observations are for September 2026. |
Sources: Eurostat, Eurosystem and ECB staff projections. Note: Data refers to import volumes. |
Source: S&P Global. Note: The latest observations are for September 2026. |
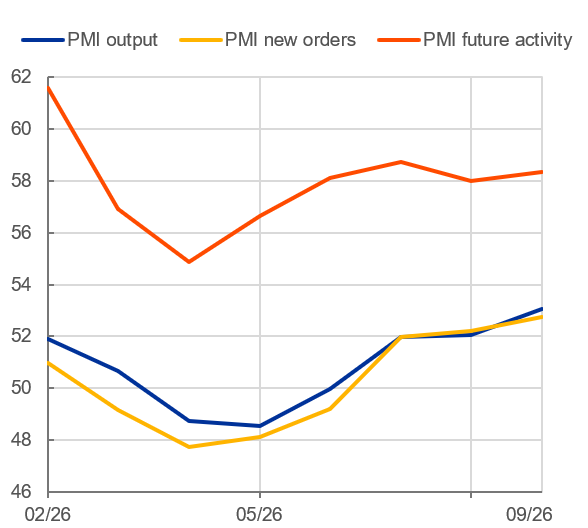
Third, AI has provided a boost to domestic demand, notably in strengthening investment. PMI indicators signal a relatively fast recovery towards pre-war levels, especially for output and new orders (Chart 5, panel a).
The AI boom has been a key factor behind these developments. If we zoom in on sectoral PMI data, it shows that the subsectors in manufacturing and services related to AI have been performing especially well (Chart 5, panel b).
Chart 5
Output and sectoral drivers – survey evidence
|
a) PMI composite for output, new orders and activity |
b) PMI for technology equipment and software compared with manufacturing and services |
|---|---|
|
(diffusion indices) |
(diffusion indices, average January-September 2026) |
|
|
|
Source: S&P Global. Note: The latest observations are for September 2026. |
Sources: S&P Global and ECB calculations. Notes: Sectoral labels are taken from the July Global PMI press release. The latest observations are for September 2026. |
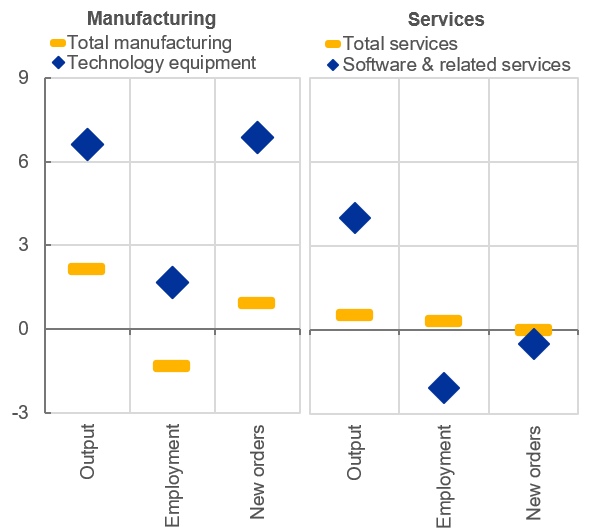
In technology equipment – the manufacturing subsector most related to AI – output, employment and new orders developed considerably more favourably than the average (Chart 5 panel b, left-hand panel).
For services, however, the software subsector, with its significant exposure to AI, performed better with respect to output but not with respect to employment and new orders (Chart 5, panel b, right-hand panel). Strong demand in AI-related subsectors means that a reversal in AI-related demand would leave parts of the economy exposed.
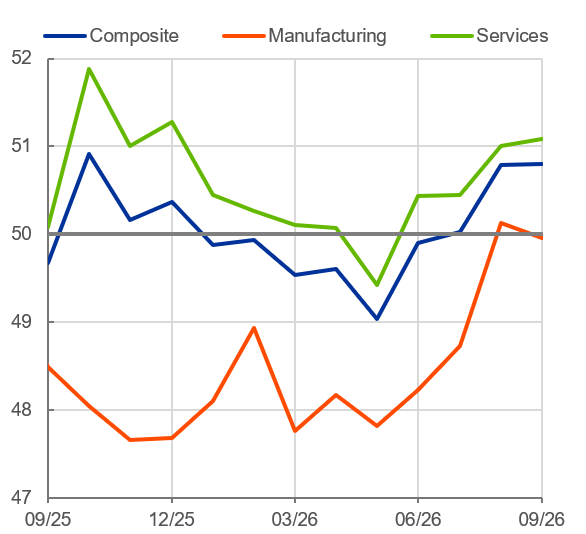
Finally, the labour market has provided an additional source of resilience. As reflected by real-time indicators, like PMI employment, the conflict in the Middle East slightly dented employment expectations. These recovered quickly, however, and now stand above their pre-war levels (Chart 6, panel a).
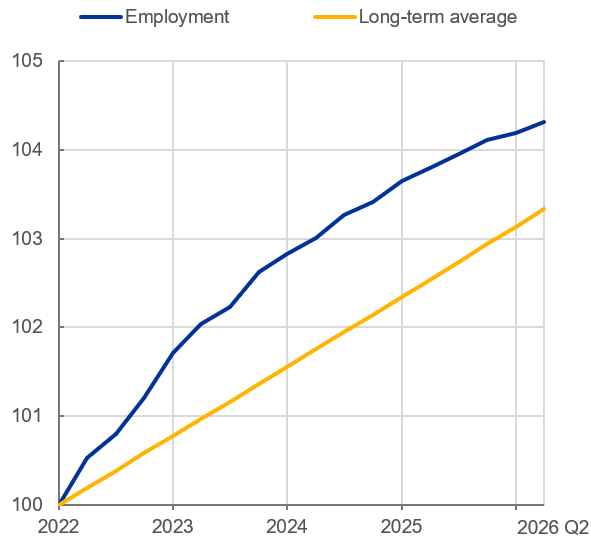
Employment has continued to rise steadily, with growth clearly higher than long-term averages since 2022. Historically, significant energy shocks often translated into weaker labour demand and rising unemployment.[15] By contrast, employment in the euro area held up much better than expected during the first half of the year and continued to expand (Chart 6, panel b). The resilient labour market has helped the euro area economy cope with the energy shock by supporting incomes and consumption.
Chart 6
Labour market developments
|
a) PMI employment |
b) Employment developments since 2022 |
|---|---|
|
(diffusion indices) |
(first quarter of 2022 = 100) |
|
|
|
Source: S&P Global. Note: The latest observations are for September 2026. |
Sources: Eurostat and ECB calculations. Notes: Long-term average corresponds to the period 2000-26. The latest observations are for the second quarter of 2026. |
Adaptive capacity: preparing for future shocks
So far, the euro area economy has held up better than expected amid the energy price shock caused by the conflict in the Middle East. Nevertheless, the outlook is highly uncertain. The euro area faces significant downside risks to growth. These include a further escalation of geopolitical conflicts, disruption of energy supply chains, a worsening of financial market sentiment, and a resurgence in trade tensions or recurrence of extreme weather events. Several of these risks are interconnected and could materialise quickly. At the same time, the factors that have cushioned the economy so far – robust global demand, the AI-related investment boom and fiscal support – may not persist, at least at their current levels.
This puts the focus on the third dimension of resilience: adaptive capacity. The recent energy shock highlights several areas where further adaptation could strengthen resilience. The first concerns energy. Continued progress in reducing dependence on imported fossil fuels could further limit the exposure of the economy to geopolitical disruptions and energy price volatility. Europe needs to make further progress on the green transition, which not only contributes to the required global cut in greenhouse gas emissions and helps reduce the further intensification of climate change and the likelihood of extreme weather, but also increases the resilience of the European economy, including by reducing dependence on imported fossil fuels. Further integration of EU electricity markets, including more cross-border interconnections and investment in grids, would also help. Cheaper renewable electricity could flow where it is needed, reducing the extent to which gas prices determine wholesale electricity prices.[16]
The second concerns innovation and technological change. Recent developments related to artificial intelligence may create important opportunities for growth and productivity. At the same time, the scale and persistence of these benefits remain uncertain and will depend on the speed of adoption and diffusion across firms and sectors.[17]
Finally, the third concerns the allocation of capital. Increasing financing needs, including those related to the energy and digital transitions, will require savings to be channelled more effectively towards productive opportunities. Swifter progress towards a deeper savings and investments union could therefore support both long-term growth and resilience.[18]
Check out The ECB Blog and subscribe for future posts.
For topics relating to banking supervision, why not have a look at The Supervision Blog?
“The European Central Bank is the prime component of the Eurosystem and the European System of Central Banks as well as one of seven institutions of the European Union. It is one of the world’s most important central banks.”
Please visit the firm link to site